
Wednesday, January 12, 2011
Initiated the Bond Pair with TBT and IEF
The TBT and IEF pair looked pretty good as interest rate may go up in the future. The inverse 2X TBT can be benefited from it where the IEF just to hedge its position.


Monday, January 10, 2011
Sold ETF losers
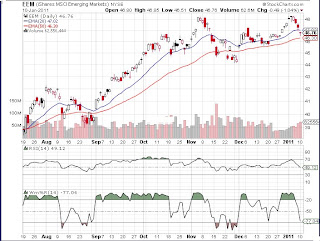
Sold EEM, EWZ and VWO at the close today to cut the loss small.
Click here for:
Ocean Portfolio Performance
Click here for:
Ocean Portfolio Performance

Sunday, January 9, 2011
Took some profits off the Bond Pairs
Took profits from the ProShares UltraShort Lehman 20+ Year Treasury (TBT) and the iShare Barclays 7-10 Year Treasury Bond (IEF). I will wait for the next signal to get back in.
Click here for the Bond Pair performance spreadsheet:
Bond Pair Performance
IWM and EFA looked weak on the TSP portfolio, took small loss and liquidated it.
Click here for the TSP portfolio performance spreadsheet
TSP Portfolio Performance
Click here for the Bond Pair performance spreadsheet:
Bond Pair Performance
IWM and EFA looked weak on the TSP portfolio, took small loss and liquidated it.
Click here for the TSP portfolio performance spreadsheet
TSP Portfolio Performance
Saturday, January 1, 2011
Happy New Year and Happy Trading in 2011
I started two portfolios in this blog with one focuses on a 2 times leverage of SSO and SDS and the other focuses on the bond pairs trading. These ETF bonds are TLT vs PST (2x inverse) and TBT (2x inverse) vs IEF. The reason that I choose reverse is that it can be traded in a retirement account where short trade is prohibited in this type of accounts.
The pairs trading will be traded with a long and short pair in the interest rate ETF bonds. I only chose the TLT (iShares Barclays 20 year treasury) vs PST (ProShares Ultra Short Lehman 7 - 10 year bond) and the TBT (ProShares Ultra Short Lehman 20 Year treasury) vs IEF (iShares Lehman 7 - 10 year treasury). The reason I chose the inverse ETF instead of short is that it can be traded in a non-margin retirement account and not paying dividend on the shorts. The pair will be traded in a non-correlated fashion comparing with the equity markets but the pair itself is highly correlated. This is to be less risky because of the nature of the correlated long and short pair in theory will go from convergence to divergence, and to convergence again from time to time as it is referred to "reverse-to-mean". The profits will be made when the pair reverses to its normal spread. For detail information on pair trading, reader can google pair trading and there are tremendous info related to pair trading or pairs trading on the internet.
As of 12/31/2010, all portfolios are fully invested based on my observation that the overall market will continue to trend up in a near term. The NYSE Advance and Decline issues indicated that this is the case at the moment. See chart below, as long as the $NYAD index stays above the 20 and 50 EMAs, the portfolios will remain the current positions.
Below is the chart on NYSE Advance and Decline Issues which indicated that the upward momentum is still strong.

The pairs trading will be traded with a long and short pair in the interest rate ETF bonds. I only chose the TLT (iShares Barclays 20 year treasury) vs PST (ProShares Ultra Short Lehman 7 - 10 year bond) and the TBT (ProShares Ultra Short Lehman 20 Year treasury) vs IEF (iShares Lehman 7 - 10 year treasury). The reason I chose the inverse ETF instead of short is that it can be traded in a non-margin retirement account and not paying dividend on the shorts. The pair will be traded in a non-correlated fashion comparing with the equity markets but the pair itself is highly correlated. This is to be less risky because of the nature of the correlated long and short pair in theory will go from convergence to divergence, and to convergence again from time to time as it is referred to "reverse-to-mean". The profits will be made when the pair reverses to its normal spread. For detail information on pair trading, reader can google pair trading and there are tremendous info related to pair trading or pairs trading on the internet.
As of 12/31/2010, all portfolios are fully invested based on my observation that the overall market will continue to trend up in a near term. The NYSE Advance and Decline issues indicated that this is the case at the moment. See chart below, as long as the $NYAD index stays above the 20 and 50 EMAs, the portfolios will remain the current positions.
Below is the chart on NYSE Advance and Decline Issues which indicated that the upward momentum is still strong.

Saturday, December 18, 2010
New start for the New Year
In order to tailor to the new format using $100,000 as an initial investment portfolio, I deleted the 2010 portfolios and started 2 new one. Needless to say the portfolios in 2010 resulted a loss and that's what the experiment was about - learn from the mistakes, march forward and not to repeat the same mistake again. The mistake was not following the stops loss strategy properly and led to the bigger loss in certain positions. On top of that I had an error with the calculation on the trailing stop loss formula on the spreadsheet.
The 2011 portfolio will start with $100,000 each on the Ocean Portfolio and TSP Portfolio. Daily moving averages cross-over will be the primary indicators as the entry point. (refer to the strategy listed on the lower right-hand side of the page). Stop loss trigger will be using a combination of ATR, RSI, ADX and Moving Averages indicators.
There were small positions in both portfolios to start off the new setup.
Happy trading and have a wonderful New Year.
Ocean
The 2011 portfolio will start with $100,000 each on the Ocean Portfolio and TSP Portfolio. Daily moving averages cross-over will be the primary indicators as the entry point. (refer to the strategy listed on the lower right-hand side of the page). Stop loss trigger will be using a combination of ATR, RSI, ADX and Moving Averages indicators.
There were small positions in both portfolios to start off the new setup.
Happy trading and have a wonderful New Year.
Ocean
Thursday, December 16, 2010

Year 2010 is coming to the end
December is half gone and the year of 2010 will soon be over. The overall stock market is considered to be good following last year's huge gain. The SPY of ETF index fund which is equivalent to S&P 500 posted a gain of 7.8% year-to-date. Meanwhile my first year Ocean Portfolio using ETFs as the investment portfolio has been disappointed due to my improper used of stops and subsequently let the loss accumulated.
In coming year, I will continue to use moving averages with cross-over as the lead indicator for trend following. I will use daily average instead of weekly and I will apply the ATR, RSI, ADX indicators as extra filters for profits and stops as opposed to the fixed percentage that I used this year.
In general, my method is as follow: the daily moving averages (DMAs) for trending following will be 20 and 50 days, when DMA-20 crosses above DMA-50, the trend is up. When DMA-20 crossed below DMA-50, the trend is down. I will start off with $100,000 each as the hypothetical portfolio for two portfolios I am tracking. (1) Ocean Portfolio and (2) TSP portfolio - the government retirement system for federal employees. I hope these two portfolios will achieve better results in 2011 than this year.
In coming year, I will continue to use moving averages with cross-over as the lead indicator for trend following. I will use daily average instead of weekly and I will apply the ATR, RSI, ADX indicators as extra filters for profits and stops as opposed to the fixed percentage that I used this year.
In general, my method is as follow: the daily moving averages (DMAs) for trending following will be 20 and 50 days, when DMA-20 crosses above DMA-50, the trend is up. When DMA-20 crossed below DMA-50, the trend is down. I will start off with $100,000 each as the hypothetical portfolio for two portfolios I am tracking. (1) Ocean Portfolio and (2) TSP portfolio - the government retirement system for federal employees. I hope these two portfolios will achieve better results in 2011 than this year.
Subscribe to:
Posts (Atom)